Understanding Condo Fees in North Oakville: What's Included and What to Watch For
Understand North Oakville condo fees — what's covered, hidden costs, reserve funds, red flags in new builds, and how fees affect mortgage approval.
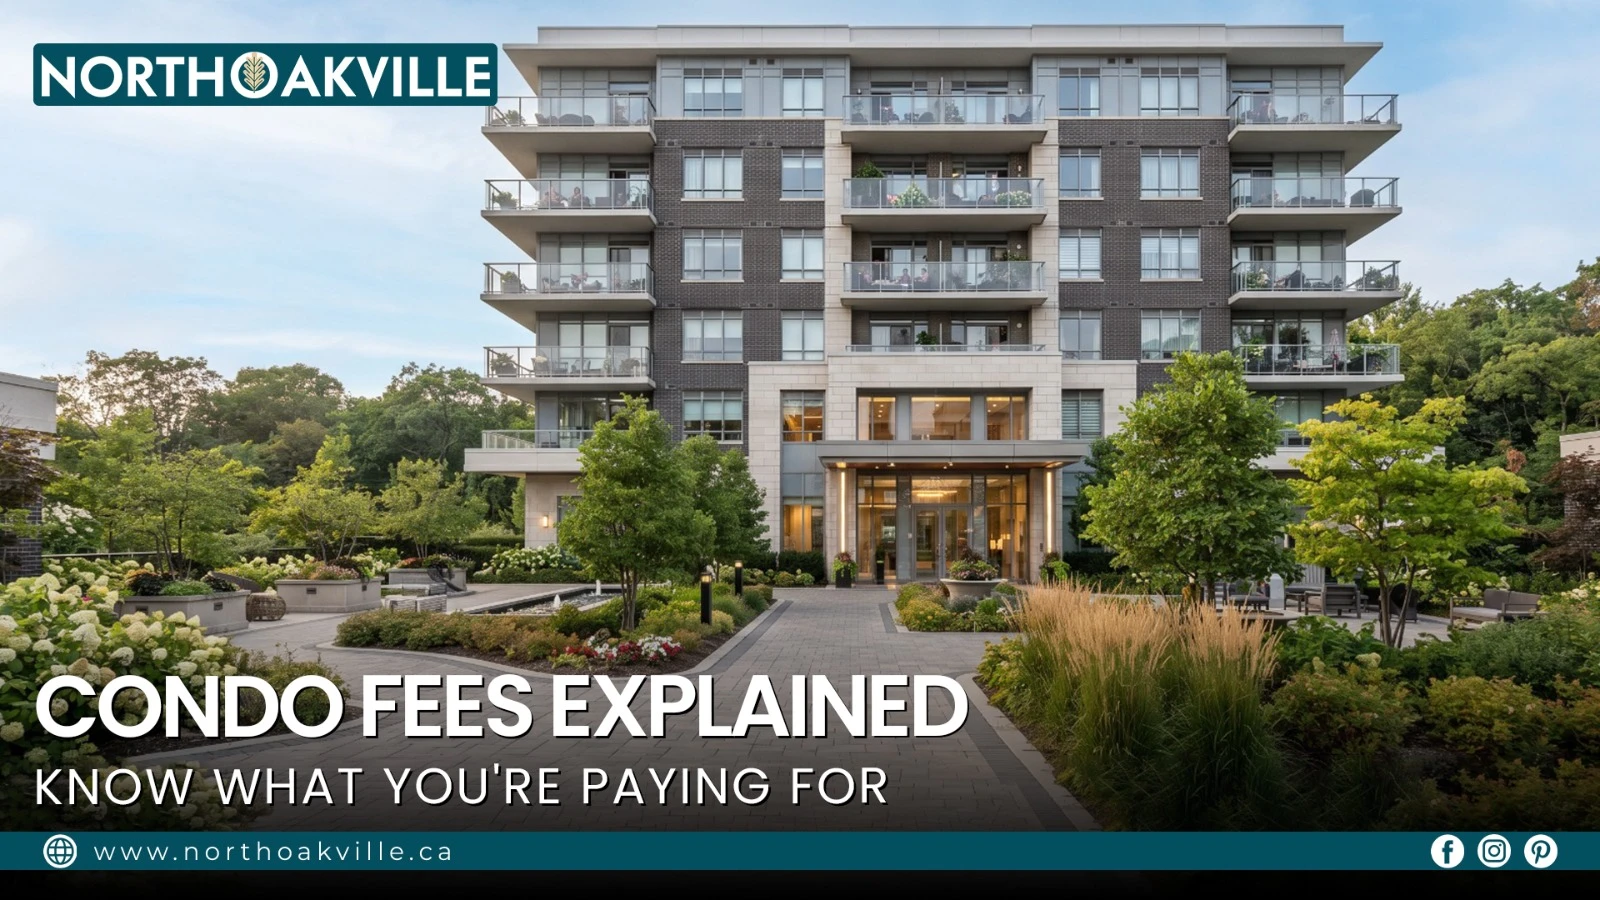
Condo fees are one of the most misunderstood line items in a home purchase. Buyers often glance at the monthly number, mentally file it under "annoying but manageable," and move on to the more exciting parts of house-hunting. That's a mistake — especially in North Oakville, where a wave of newer construction has created its own set of quirks, from unbundled utilities to first-year budgets that don't tell the whole story. This guide breaks down exactly what you're paying for, what's missing from that monthly number, and how to protect yourself before you sign.
What Condo Fees Actually Are
Condo fees aren't an arbitrary number a developer picks out of thin air. Each year, the condo corporation calculates the total cost of running the building — everything from cleaning contracts to insurance to reserve fund savings — and divides that cost among owners based on their percentage of ownership interest, which is typically tied to unit size.
In North Oakville's newer developments, fees generally fall in the $0.55 to $0.70 per square foot (PSF) range per month. For context, a 700-square-foot one-bedroom unit in a newer mid-rise would land somewhere around $385 to $490 a month.
You'll hear three terms used almost interchangeably: condo fees, maintenance fees, and common element fees. In everyday conversation they mean the same thing — what you pay monthly to keep the building running. "Common element fees" generally refers to your proportional share of maintaining everything outside your unit's boundaries, as defined in the building's legal Declaration under the Condominium Act — though the exact terminology and boundaries can vary somewhat by building.
How North Oakville Compares Regionally
Region | Typical Fee Range (PSF) | Why |
|---|---|---|
North Oakville | $0.55 – $0.70 | Newer builds, heavily unbundled utilities |
Older/Lakeshore Oakville | $0.80 – $1.10+ | Premium towers, more concierge/amenity staffing |
Mississauga (e.g., Square One area) | $0.75 – $1.10 | High-density towers with extensive amenities |
Burlington | $0.60 – $0.85 | Mix of newer transit-oriented builds and older lakefront stock |
Milton | $0.50 – $0.65 | Lower-rise wood-frame construction, fewer amenities |
North Oakville sits on the lower-to-middle end of this range largely because so much of its housing stock is new, energy-efficient, and built with unbundled utilities — meaning the condo fee itself looks leaner, even if your total monthly housing cost isn't necessarily lower once you add everything up (more on that below).
How Fast Do Fees Rise, and Why?
A well-managed building should see fees climb roughly 3% to 6% a year to keep pace with inflation. If a building boasts zero increases for several years running, that's often a red flag rather than good news — it can mean the board is under-collecting and quietly starving the reserve fund.
The most common drivers of annual increases are rising costs for service contracts (cleaning, snow removal, security), climbing commercial building insurance premiums across the GTA, and periodic reserve fund top-ups following a mandatory reserve fund study.
Does a Building's Age Matter?
Yes, in both directions. Older buildings (15+ years) tend to cost more as major systems — elevators, parking garage membranes, HVAC — start reaching the end of their useful life around the same time, and older mechanical and insulation systems tend to run less efficiently. Newer buildings (0–5 years) often look cheaper on paper, but developers frequently set an artificially low first-year budget to make units more attractive to buyers. Once the owner-elected board takes over — often somewhere between year two and year four — a budget correction can push fees up noticeably in a single year as real operating costs get reflected for the first time.
What Condo Fees Include
When you pay your monthly condo fee, that money gets split across several distinct operational buckets. Here's exactly what each dollar is working toward.
Common Element Maintenance
This is the bulk of what your fee covers day to day: cleaning of lobbies, hallways, and stairwells; landscaping and seasonal grounds work; snow plowing and salting for shared walkways and roads; and routine servicing and safety inspections for elevators, HVAC systems, fire alarms, and security infrastructure.
The Reserve Fund Contribution
Every condo corporation in Ontario is legally required to maintain a reserve fund — a dedicated savings account used only for major, non-routine capital repairs, like replacing a roof or repaving a garage. In a typical North Oakville building, a meaningful share of your monthly fee — commonly cited as somewhere around 20% to 30%, though this varies by corporation — goes into this fund. Under Section 94 of the Ontario Condominium Act, an independent engineer must conduct a reserve fund study at least every three years to project repair needs over a 30-year horizon and recommend how much the corporation should be collecting.
Building (Master) Insurance
It's a common misconception that the condo corporation's insurance covers everything. In reality, it's a two-policy system:
Insurance Type | Who Pays | What It Covers |
|---|---|---|
Master building insurance | Included in condo fees | The physical structure, common areas, and standard unit finishes as originally built |
Personal condo insurance (often called HO-6) | Paid separately by the owner | Your belongings, personal liability, any post-construction upgrades, and typically your deductible if damage originates in your unit |
Shared Amenities & Professional Management
Amenities like a pool or 24/7 concierge add real, ongoing cost — pools need constant chemical balancing, heating, and pump maintenance, while staffed security or concierge desks mean funding salaries around the clock. Gyms, party rooms, and visitor parking cost less to maintain by comparison. On the administrative side, professional property management typically accounts for a modest share of the overall budget — generally in the single digits as a percentage — with the bulk of your fee going toward the physical building itself rather than management overhead.
Utilities: What's Usually Bundled
In most North Oakville buildings built over the last decade, hydro, heating, and cooling are individually sub-metered and unbundled — you pay a utility provider directly for your own usage. Water and sewage costs, by contrast, are still commonly bundled into the base condo fee, since retrofitting individual water metering per unit is complex. Some newer buildings also roll a bulk-negotiated internet or cable package into the condo fee at a discounted rate.
What's NOT Included — and the Costs That Catch Buyers Off Guard
While condo fees cover the shared spaces, plenty of real costs sit just outside that monthly number — and they're often the ones buyers overlook until the first bill arrives.
Unbundled Utilities
Because heating, cooling, and hydro are usually billed separately in newer North Oakville buildings, expect a fixed monthly administration and meter-rental charge from the sub-metering company on top of your actual usage — commonly landing somewhere in the range of an extra $30–$50 a month before you've used a single kilowatt. Buildings using leased HVAC or geothermal infrastructure can add a further monthly equipment charge on top of that. Always ask what these add-on charges look like before you buy — they don't show up in the advertised condo fee.
Property Taxes & Personal Insurance
Your condo fee generally stops at your unit's front door, though exact boundaries depend on the building's Declaration. Property taxes are billed directly by the Town of Oakville, since your unit is assessed as its own distinct piece of real estate. Similarly, the building's master insurance only restores your unit to its original, "as-built" condition — it doesn't cover your furniture, electronics, or any personal upgrades. That's what a personal HO-6 policy is for.
Special Assessments & Chargebacks
These are the two scenarios that catch owners most off guard financially:
A special assessment is an extra, one-time levy billed to all owners when the reserve fund can't cover an unexpected major expense — a burst pipe, a structural repair, or a lost lawsuit, for example. These can range from a few thousand dollars to well over $20,000 per unit in serious cases.
A chargeback happens when an expense is caused specifically by your unit — say, a leaking washing machine hose that damages the unit below — and the corporation bills the repair cost directly back to you.
The best defence against both is reviewing the building's status certificate carefully before buying, and making sure your personal insurance includes loss assessment coverage.
Parking & Locker Fees
In North Oakville, parking spots and storage lockers are often treated as separate titled property rather than bundled automatically into your unit, though the exact arrangement depends on the building's Declaration. Where they're separate, that typically means a separate purchase cost plus a separate ongoing monthly fee for each — often in the ballpark of $40–$60 a month for a parking spot and $15–$25 a month for a locker, on top of your unit's own condo fee.
Red Flags to Watch For — Especially in New Builds
Not every condo building is financially healthy, and the difference between a well-run corporation and a future financial headache usually comes down to a handful of things worth checking before you buy.
The "Low First-Year Fee" Trap
Pre-construction marketing loves a low monthly fee number. The problem is that first-year budgets are estimates made before the building is even occupied, and they routinely underestimate real-world costs. Once an elected owner board takes over — commonly within the first one to a few years — an updated operating budget and reserve fund study often reveals the true cost of running the building, and a noticeable one-time fee correction can follow.
Reading the Reserve Fund Study
Ask to see the building's most recent reserve fund study and pay attention to the funding plan section, which lays out how much the engineer recommends the corporation collect each year. If the board is collecting meaningfully less than what's recommended, a future fee increase — or worse, a special assessment — becomes far more likely.
Warning Signs of an Underfunded Reserve
A few patterns should raise a flag: multiple consecutive years with no fee increase at all (often a sign fees are being artificially suppressed), a reserve fund balance that looks thin relative to the building's age, or a history of past special assessments — which tells you the regular monthly fees haven't been enough to sustain the property.
The Status Certificate
This is arguably the single most important document in a condo purchase. Under the Condominium Act, it's required to include prescribed information such as whether the seller owes any back fees or fines, the current operating budget and reserve fund balance, and whether the corporation is facing any lawsuits or has a special assessment underway. Any condo offer should be conditional on a lawyer reviewing this document before the deal firms up.
Can Fees Be Negotiated?
No — not at purchase, and not afterward. Your fee is tied strictly to your unit's percentage of ownership interest as set out in the building's Declaration. Not using the gym, living on the ground floor, or travelling frequently doesn't reduce your legal obligation to pay your share.
Financial Planning: What Condo Fees Mean for Your Budget
Condo fees don't just affect your monthly cash flow — they shape how much home you can borrow, how a building compares to its neighbours, and even how easily your unit resells down the road.
Mortgage Qualification
Lenders don't ignore condo fees when calculating how much mortgage you qualify for. Many lenders, including under CMHC-insured lending guidelines, count roughly 50% of your monthly condo fee toward your housing costs when calculating your Gross Debt Service (GDS) and Total Debt Service (TDS) ratios — though the exact treatment can vary by lender and mortgage type. In practical terms, a higher condo fee tends to reduce the maximum mortgage amount a lender will approve you for — so it's worth factoring into your budget early, not after you've fallen in love with a unit.
Building Style Comparison
The architectural style of a building has a direct effect on its operating costs:
Building Type | Typical Fee Range (PSF) | Why |
|---|---|---|
High-rise towers | $0.65 – $0.85+ | More elevators, complex mechanical systems, amenity-heavy, often staffed |
Low-to-mid-rise (4–6 storeys) | $0.55 – $0.70 | Simpler mechanical footprint, fewer or no staffed amenities |
Condo townhouses | $0.40 – $0.55 | Fees cover shared roads, snow removal, and common grounds; exterior building maintenance shared among fewer units |
Amenity-heavy buildings — think heated pool, full gym, and a staffed concierge — can run 20–35% higher than a no-frills building with basic entry security and minimal shared facilities.
Note that POTL (Parcel of Tied Land) freehold townhomes are a different structure entirely and don't compare naturally on a per-square-foot basis — they charge a flat monthly common expense fee (typically $80–$200) rather than a PSF-based condo fee, since the owner, not a condo corporation, owns and maintains the building itself.
Resale Value: A Double-Edged Signal
Moderate, steadily rising fees paired with a healthy reserve fund generally read as a positive signal to resale buyers — it suggests the building is financially sound. Fees that sit noticeably above the local average, on the other hand, can scare off first-time buyers who are already stretched on their mortgage ratios, which can mean units sit on the market longer.
Condo vs. Freehold: The Long-Term Math
Over a 10-to-15-year window, the total cost of ownership between a condo and a comparable freehold townhouse often ends up fairly close — it's really a question of how you pay. A condo fee acts like forced savings: when the roof eventually needs replacing, the money is already there. A freehold owner pays nothing monthly but has to be ready to write a large, unplanned cheque — often well into five figures — when a major system fails.
Building Size and Economies of Scale
Larger buildings generally spread big-ticket costs (a roof, an elevator overhaul, a flat management fee) across more owners, which can make per-unit fees more efficient. Smaller, boutique buildings — often under 60 units — don't have that cushion, so a single major repair can hit each owner's share (or reserve fund) much harder.
Legal & Governance: What Owners Can and Can't Control
Under the Ontario Condominium Act, the elected condo board — not individual owners — holds the legal authority to set and approve the annual budget and any resulting fee increases. Owners don't vote directly on the budget itself, though the board must provide a copy at least 15 days before the new fiscal year begins, and owners retain meaningful oversight tools of their own, covered below.
Importantly, there is no legal cap on how much a condo board can raise fees in Ontario — unlike residential rent control for tenants. If insurance premiums spike or an emergency repair is required, the board is legally obligated to raise the funds needed, regardless of the percentage increase involved.
That said, owners aren't powerless. At the mandatory Annual General Meeting (AGM), owners can review audited financial statements and question the board's spending decisions. Owners can also run for a board seat themselves, or — under Section 46 of the Act — a group representing a meaningful share of unit owners can formally requisition a special meeting to raise financial concerns.
If fees go unpaid, the corporation has powerful legal tools: it can register a Certificate of Lien against the unit's title, generally within a strict window after the default. Once registered, that lien typically takes priority over even the owner's mortgage, and non-payment can ultimately lead to a forced sale of the unit — much like a bank's power of sale.
Sellers, for their part, are legally required to disclose the current fee amount, any default on payments, and whether a fee increase or special assessment is planned or underway — all of which shows up in the status certificate.
North Oakville's Condo Fee Landscape
North Oakville's fee structures are shaped heavily by how recently a building was constructed and how its utilities are set up. Newer buildings that aggressively unbundle utilities and skip expensive amenities like indoor pools tend to sit toward the lower end of the local range, while boutique or premium buildings with fuller amenity packages and fewer units to share costs across trend higher.
The area is also a hub for energy-efficient construction, with some newer communities using geothermal heating and cooling. This tends to keep the base condo fee lean, since it removes bulky, carbon-intensive mechanical systems from the building's shared budget — but it typically shifts the cost elsewhere, onto a separate monthly geothermal or HVAC infrastructure fee billed by a third-party utility provider. The takeaway for buyers: a lean-looking condo fee in a "green" building doesn't necessarily mean a lower total monthly housing cost — it's worth asking what utility-related fees exist outside the condo fee itself.
Who Should Pay Closest Attention
First-time buyers are often stretched to their maximum approved mortgage amount, so a higher-than-expected condo fee can meaningfully shrink what they qualify for — and a first-year budget correction or surprise assessment can hit hardest when there's little financial cushion.
Investors need to watch condo fees closely because, in Ontario, a landlord can't simply raise rent mid-lease to offset a jump in fees — a sudden increase eats directly into cash flow and cap rate.
Downsizing retirees love the "lock-and-leave" appeal of condo living, but should be mindful that fixed retirement income doesn't always keep pace with rising fees, and a poorly funded reserve can mean a large special assessment years into ownership.
Anyone comparing buildings with rental restrictions should know that buildings with tighter rules around short-term or transient rentals often see less wear and tear on shared spaces, which can support steadier, more predictable fees over time — though insurance premiums depend on many other factors too.
A Practical Buyer's Checklist
Request the full status certificate package — never rely on a listing description or a walkthrough alone. This should include the status certificate itself, the most recent reserve fund study, the current operating budget, the latest audited financial statements, and the building's rules and bylaws.
Have a real estate lawyer review it thoroughly during your conditional period, specifically checking the reserve fund's health and whether the board is collecting what the engineers recommend.
Ask your realtor to benchmark the fee against similar buildings of a comparable age and size in the area — a fee that's dramatically higher or lower than nearby comparables is worth investigating further.
Ask directly about unbundled utility costs — sub-metering, geothermal, or HVAC rental fees aren't part of the condo fee but are part of your real monthly cost.
Confirm parking and locker fees separately, since these are frequently billed apart from the unit's own condo fee.
Common Myths, Cleared Up
"Condo fees are money down the drain — freehold is always better." Not necessarily. Part of your fee is really a forced savings plan for large capital repairs that a freehold owner would otherwise have to fund entirely out of pocket, all at once.
"I don't use the gym or pool, so I should get a discount." Fees are tied to your ownership share, not your personal usage — there's no legal basis to request a reduction.
"The fees are low now, so they'll stay low." Especially in new construction, an initially low fee is often a first-year estimate rather than a long-term number — budget for the possibility of a correction down the road.
Final Thoughts
Condo fees in North Oakville aren't just a monthly nuisance — they're a window into how well a building is being run and how prepared it is for the future. A fee that looks unusually low should raise questions just as much as one that looks unusually high. Before you buy, ask for the paperwork, get a lawyer to review it properly, and factor in the costs that live just outside the condo fee itself — utilities, parking, and the occasional special assessment. Do that groundwork, and a condo fee stops being a mystery line item and becomes exactly what it should be: a predictable, manageable part of owning in North Oakville.
FAQs
Do condo fees include property taxes in Ontario?
No. Condo fees fund the operation and maintenance of the building and its common elements only. Property taxes are assessed and billed separately, directly to the owner, by the municipality.
Is there a legal limit or cap on condo fee increases in Ontario?
No. Unlike residential rent control for tenants, condo boards are legally required to set fees according to the actual cost of running the building, with no percentage cap on how much they can increase in a given year.
What is a reasonable condo fee per square foot in North Oakville?
For newer mid-rise and high-rise buildings, a fee in the roughly $0.55 to $0.70 per square foot range is typical. Older buildings or those with extensive amenities like a 24/7 concierge and indoor pool often run higher, sometimes $0.80 to $1.10+ per square foot.
What happens if I don't pay my condo fees?
The corporation can register a Certificate of Lien against your unit, generally within a few months of the default. That lien typically ranks ahead of your mortgage, and continued non-payment can ultimately lead to a forced sale of the unit to recover what's owed.
What's the difference between a condo townhouse fee and a POTL fee?
A condo townhouse fee (often $400–$800+ a month) covers exterior maintenance of the structure itself — roof, windows, siding — along with shared grounds. A POTL (Parcel of Tied Land) fee, typically much lower ($80–$200 a month), applies to freehold townhomes and covers only shared elements like private roads, snow plowing, and visitor parking, since the owner maintains their own roof and exterior.
Are condo maintenance fees tax-deductible?
It depends on how the property is used. If you're renting the unit out as an investment, condo fees are generally deductible against your rental income. If you live in the unit as your primary residence, they are not deductible on your personal tax return.